Stocked Up, Strapped for Cash: How Inventory Can Quietly Drain Your Business's Financial Health
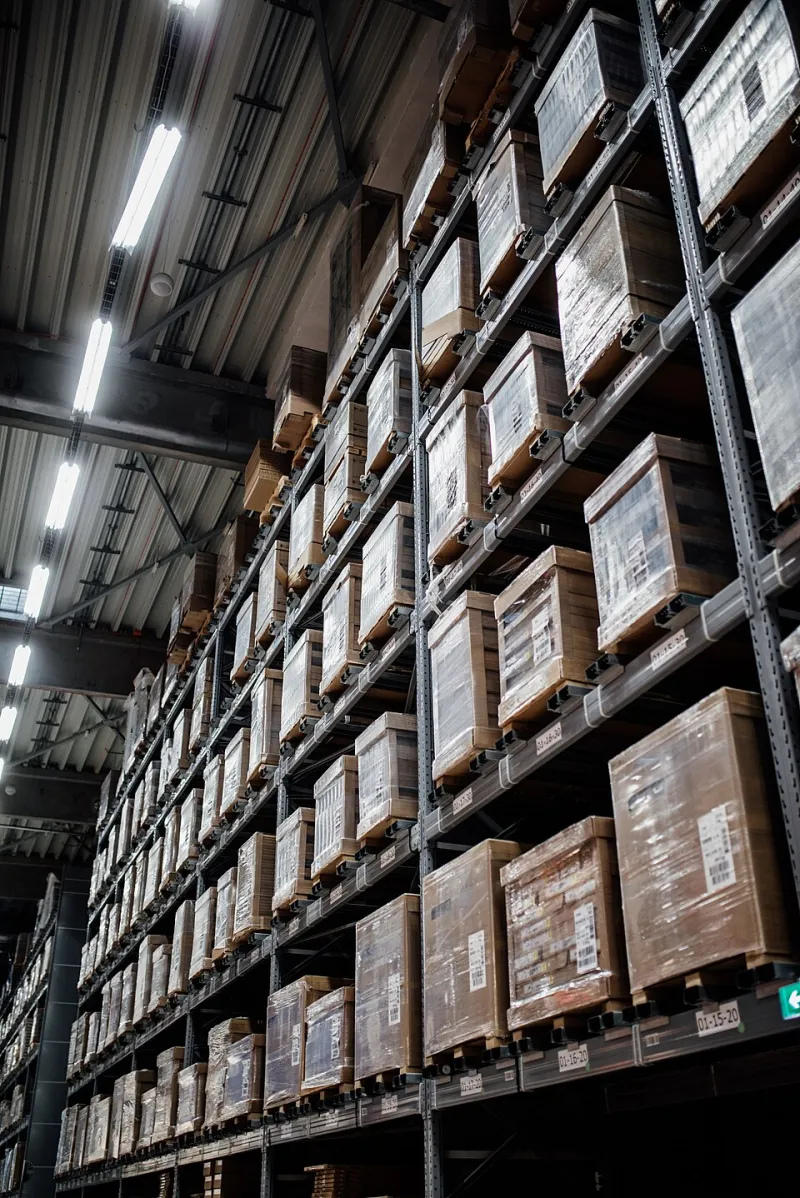
Photo: Shixart1985, CC BY 2.0, via Wikimedia Commons
There is a particular kind of financial confidence that comes from walking through a warehouse full of product. Shelves lined with merchandise, pallets stacked to the rafters, and a balance sheet that reflects hundreds of thousands of dollars in assets—it feels like prosperity. For many small and mid-size business owners across the United States, that feeling is one of the most dangerous illusions in commerce.
Inventory is an asset in the accounting sense of the word. But assets do not pay your vendors, meet your payroll, or cover the lease on your facility. Cash does. And when capital is tied up in products that are not moving, the business that looks healthy on paper can be quietly suffocating in practice.
The Gap Between Assets and Liquidity
Balance sheets present a snapshot of what a business owns and owes at a given moment in time. Inventory appears as a current asset, typically grouped alongside accounts receivable and cash. This classification implies that inventory is readily convertible to cash—and in theory, it is. In practice, the conversion depends entirely on whether customers are actually purchasing the product.
When inventory turnover slows, that current asset becomes something closer to a frozen asset. The business has already paid suppliers for the goods, absorbed the cost of storage, and allocated labor and logistics resources to manage it. Those are real expenditures. The return on those expenditures, however, is deferred indefinitely until a sale occurs.
For businesses operating on tight margins or carrying debt obligations, that deferral can be catastrophic. Vendors expect payment on net terms. Landlords expect rent on the first of the month. Neither party is interested in your inventory valuation.
Calculating Inventory Efficiency: The Numbers That Matter
The most direct measure of how effectively a business is converting stock into revenue is the inventory turnover ratio. This figure is calculated by dividing the cost of goods sold (COGS) over a given period by the average inventory value during that same period.
For example, if a product-based business reports $900,000 in COGS over a fiscal year and carries an average inventory value of $300,000, the turnover ratio is 3.0. That means the business cycles through its entire inventory approximately three times per year.
Whether that number is healthy depends heavily on the industry. A grocery distributor with a ratio of 3.0 would be in serious trouble. A specialty machinery dealer with the same ratio might be performing well. Benchmarking against industry standards—available through resources such as the U.S. Census Bureau's annual retail trade surveys or industry-specific trade associations—is essential context.
A complementary metric is days inventory outstanding (DIO), which estimates how many days, on average, inventory sits on hand before being sold. It is calculated by dividing average inventory by COGS and multiplying by 365. A rising DIO over successive quarters is a reliable early warning signal that capital is accumulating in unsold stock.
When Stock Becomes a Liability
Inventory transitions from asset to liability in several recognizable patterns. Understanding these patterns allows business owners and their accounting advisors to intervene before the damage compounds.
Overbuying based on optimistic forecasts. Many businesses scale up purchasing in anticipation of demand that fails to materialize. This is particularly common following an unusually strong sales period, when owners assume the trend will continue. The result is excess stock that ties up capital and incurs ongoing carrying costs.
Seasonal misalignment. A product that sells well in November may sit untouched through February. If purchasing cycles are not carefully calibrated to seasonal demand patterns, businesses can find themselves cash-constrained during the very periods when operational expenses remain constant.
Product obsolescence. In industries where product lines evolve quickly—consumer electronics, apparel, and technology accessories among them—inventory that was purchased six months ago may already be declining in value. Carrying that inventory at original cost on the balance sheet overstates the business's true financial position.
Supplier incentives that encourage overborrowing. Volume discounts and bulk purchase incentives from suppliers can appear attractive in isolation. However, purchasing more than demand warrants in order to secure a lower per-unit cost is a trade-off that frequently backfires when the resulting inventory does not move at the expected pace.
Real Consequences: What This Looks Like in Practice
Consider a mid-size home goods retailer operating in the Southeast. After two consecutive strong holiday seasons, ownership approved a significant expansion of their spring inventory order, confident that consumer demand would continue its upward trajectory. When sales softened due to broader economic headwinds, the business found itself holding approximately $420,000 in excess inventory entering the summer months.
The company was technically profitable. Revenue covered costs on paper. But the cash position told a different story: accounts payable were aging, a line of credit was near its limit, and the business was unable to take advantage of a favorable lease renewal opportunity because it lacked the liquidity to fund a modest buildout.
The inventory was not worthless. But it was inaccessible in any immediate financial sense. Correcting the situation required a combination of promotional discounting, consignment arrangements with secondary retailers, and a temporary suspension of new purchasing—all of which carried their own costs and operational friction.
This is not an unusual scenario. It is, in fact, one of the most common patterns that professional accountants encounter when working with product-based businesses that have been growing quickly without proportionate financial oversight.
Converting Dead Inventory into Working Capital
Once excess inventory is identified, the priority is converting it back into usable capital as efficiently as possible. Several approaches are worth considering, depending on the nature of the inventory and the urgency of the liquidity need.
Promotional pricing and clearance events are the most direct route. Accepting a lower margin on slow-moving stock is almost always preferable to the ongoing cost of carrying it. The recovered cash can be redeployed immediately.
Business-to-business liquidation channels allow companies to offload inventory in volume to secondary market buyers, discount retailers, or liquidation platforms. The return is typically below wholesale cost, but the transaction is clean and fast.
Inventory-backed financing is another option. Some lenders will extend short-term credit lines secured by inventory value, providing immediate liquidity without requiring a sale. This approach carries its own risks and should be evaluated carefully with a financial advisor.
Renegotiating supplier terms can prevent the problem from recurring. Many suppliers are willing to accommodate smaller, more frequent orders in exchange for a consistent purchasing relationship, which reduces the risk of over-accumulation.
The Role of Proactive Accounting
Inventory management is, at its core, a financial discipline. The businesses that navigate it most successfully are those that treat their inventory data as a live financial instrument rather than a static balance sheet entry. That requires regular reconciliation, consistent tracking of turnover metrics, and a willingness to act on unfavorable trends before they become emergencies.
At BPA Cal, we work with product-based businesses at every stage of growth to build the financial visibility that prevents these situations from developing undetected. A thorough review of inventory efficiency, purchasing cycles, and cash conversion timelines can reveal vulnerabilities that no amount of revenue growth will automatically resolve.
The warehouse full of product may look like success. But the only measure of financial health that ultimately matters is whether the business has the cash to operate, adapt, and grow. Inventory that cannot be converted into that cash is not an asset—it is a liability wearing a convincing disguise.