Profitable but Broke: Understanding Why Growing Businesses Run Out of Cash
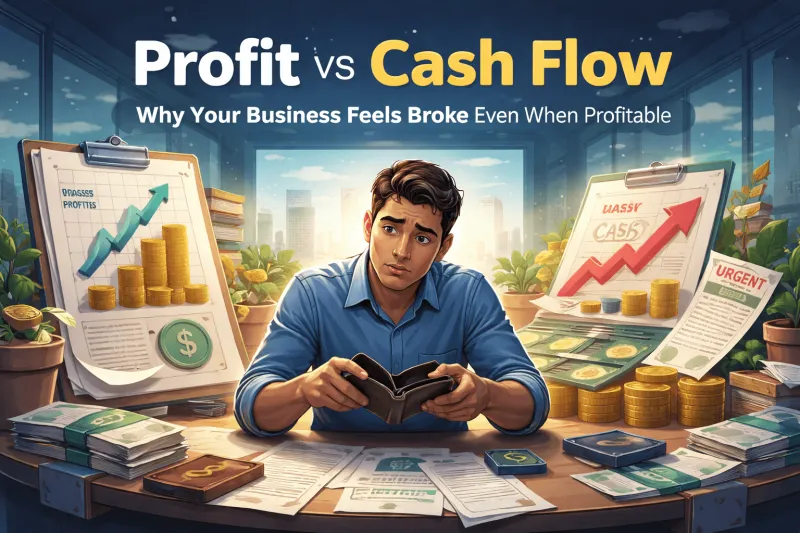
Photo: business owner stressed looking at cash flow statement and empty wallet, via blog.managekaro.org
Here is a scenario that plays out in small and mid-size businesses across the United States with troubling regularity: A business owner reviews their income statement and sees a profit. Revenue is up. The accountant confirms the numbers look solid. And yet, the checking account is nearly empty, a vendor payment is overdue, and payroll is three days away with insufficient funds to cover it.
This is not a story about poor management or reckless spending. It is a story about the gap between profit and cash—a gap that accounting statements can obscure and that business owners, particularly those in growth phases, frequently underestimate until it becomes a genuine emergency.
Profit Is an Opinion. Cash Is a Fact.
This phrase is something of a maxim in professional accounting circles, and it captures an important truth. Net income, as reported on an income statement, is calculated using accrual accounting principles. Revenue is recognized when it is earned—not when payment is received. Expenses are recorded when they are incurred—not necessarily when they are paid. The result is a financial picture that can look healthy even when the actual flow of cash through the business tells a very different story.
Consider a consulting firm that completes a $50,000 project in December. Under accrual accounting, that revenue appears on the December income statement. But if the client has a 60-day payment term, the cash does not arrive until February. In the meantime, the firm still owes its contractors, its rent, and its payroll—all of which are due regardless of when the client pays.
That firm is profitable. It is also, temporarily, cash-constrained. And if this pattern repeats across multiple clients and projects, the constraint becomes structural rather than temporary.
The Working Capital Problem That Grows With Your Business
Working capital—the difference between current assets and current liabilities—is the financial cushion that allows a business to operate day-to-day. When a business is growing, working capital requirements typically expand faster than most owners anticipate.
A company that doubles its revenue often needs to carry twice as much inventory, extend credit to more customers simultaneously, and pay suppliers before collecting from clients. Each of these dynamics consumes cash. If the business is not capitalized appropriately for that growth, it can find itself in the paradoxical position of needing more money precisely because it is succeeding.
This is not a theoretical risk. According to data regularly cited by the Small Business Administration and various financial research organizations, cash flow problems are among the leading contributors to small business failure—even among businesses that are technically profitable at the time they close.
Timing Mismatches Are the Mechanism, Not the Cause
The root issue, in most cases, is not that a business lacks profitability. It is that the timing of cash inflows and outflows is misaligned in ways that are not immediately visible on standard financial reports.
A retail business may purchase significant inventory in October to prepare for the holiday season, paying suppliers in full before a single sale is made. A construction company may be required to front labor and materials costs for weeks before billing a client at project milestones. A staffing agency pays its employees weekly but invoices clients on net-30 or net-60 terms.
In each case, cash leaves the business before it arrives. When the gap is small and the business has adequate reserves, this is manageable. When the gap widens—due to growth, seasonality, slower collections, or unexpected expenses—the business begins to feel the strain even as its income statement remains positive.
Seasonal Pressures Amplify the Problem
For many US businesses, cash flow challenges are not evenly distributed across the calendar year. Seasonal fluctuations can create periods of significant cash pressure even for businesses that are profitable on an annual basis.
A landscaping company in the Midwest may generate the majority of its revenue between April and October, while fixed costs—insurance, equipment payments, administrative overhead—continue through the winter months. A tax preparation firm faces the inverse: high demand and strong cash inflows in the first quarter, followed by months of lower activity that must be funded from reserves built during the busy season.
Without a cash flow forecast that accounts for these seasonal patterns, business owners often find themselves surprised by shortfalls that were, in retrospect, entirely predictable.
What Cash Flow Forecasting Actually Looks Like
A cash flow forecast is not simply a projection of future sales. It is a week-by-week or month-by-month estimate of when cash will actually enter and leave the business, based on realistic assumptions about payment timing, expense schedules, and anticipated revenue.
An effective forecast will account for:
- Accounts receivable aging: How long do customers actually take to pay, not how long they are supposed to take?
- Accounts payable timing: When are vendor payments due, and are there opportunities to align outflows more strategically?
- Debt service obligations: Loan payments, lines of credit, and equipment financing all represent fixed cash commitments that must be incorporated.
- Tax obligations: Quarterly estimated tax payments are a recurring cash outflow that can catch underprepared business owners off guard.
- Capital expenditure plans: Equipment purchases or facility investments require cash planning well in advance.
Building this forecast requires a working knowledge of the business's financial history and an understanding of accrual versus cash-basis reporting. It is not a task that standard accounting software performs automatically, and it is not something that can be reliably assembled from a bank statement alone.
Practical Steps to Improve Cash Visibility Before a Crisis Develops
The businesses that manage cash flow most effectively do not wait for a shortfall to prompt action. They build visibility into their financial operations as a standard practice.
Some of the most impactful steps include:
Tighten your collections process. Slow-paying clients are one of the most common contributors to cash flow stress. Establishing clear payment terms, sending invoices promptly, and following up consistently on overdue accounts can meaningfully accelerate cash inflows without requiring any additional revenue.
Review your payment terms with vendors. Many suppliers offer flexibility in payment timing that businesses never negotiate. Extending payables by even 15 to 30 days, where appropriate, can smooth the mismatch between inflows and outflows.
Establish a credit facility before you need it. A business line of credit is most accessible when your financials are strong. Applying during a cash crisis—when lenders can see the stress in your statements—is far more difficult. Establishing credit proactively provides a buffer that costs nothing until it is used.
Separate your cash flow statement from your income statement. Review both, regularly, with the same level of attention. Profit is important. Cash is what keeps the business operating.
Work with a professional to build a rolling 13-week cash forecast. This tool, common in corporate finance but underutilized among small businesses, provides a granular view of cash position in the near term and allows for proactive decision-making rather than reactive crisis management.
The Cost of Waiting
Cash flow problems rarely announce themselves far in advance. They tend to surface suddenly—a payroll date arrives with insufficient funds, a supplier demands payment that cannot be met, a line of credit that was assumed to be available turns out to be fully drawn. By that point, the options available to a business owner are narrower and more expensive than they would have been with earlier visibility.
The businesses that avoid this trap are not necessarily better managed in every respect. They are simply better informed. They understand that profit is a measure of performance and cash is a measure of survival—and they treat both with equal seriousness.
At BPA Cal, we help business owners build the financial infrastructure to see cash flow clearly, plan proactively, and grow with confidence rather than anxiety. If your income statement looks strong but your bank account tells a different story, it is worth having a conversation about what the numbers are not showing you.